Is it safe to borrow from a private finance company in Kerala is a question worth asking before you sign any agreement, especially with banks often slow and rigid for self-employed and informal-income applicants. Private financiers and NBFCs have become a go-to option across the state — but not all of them operate legally or fairly.
This guide breaks down exactly how to check legitimacy, what red flags to watch for, and how registered lenders differ from informal ones.
Is It Safe to Borrow from a Private Finance Company in Kerala? Understanding the Basics
Kerala has a long history of informal lending — local financiers, chit funds, and unregistered moneylenders operating on trust and reputation. So, is it safe to borrow from a private finance company in Kerala? The honest answer: it depends entirely on whether the lender is registered and regulated, not on how “private” it sounds.
The key distinction is whether a lender is registered under the Kerala Money Lenders Act registration framework or operates outside any regulatory oversight. Registered lenders follow:
- Capped, transparent interest rates
- Mandatory written agreements
- Regulated recovery practices
- Documented KYC and loan processes
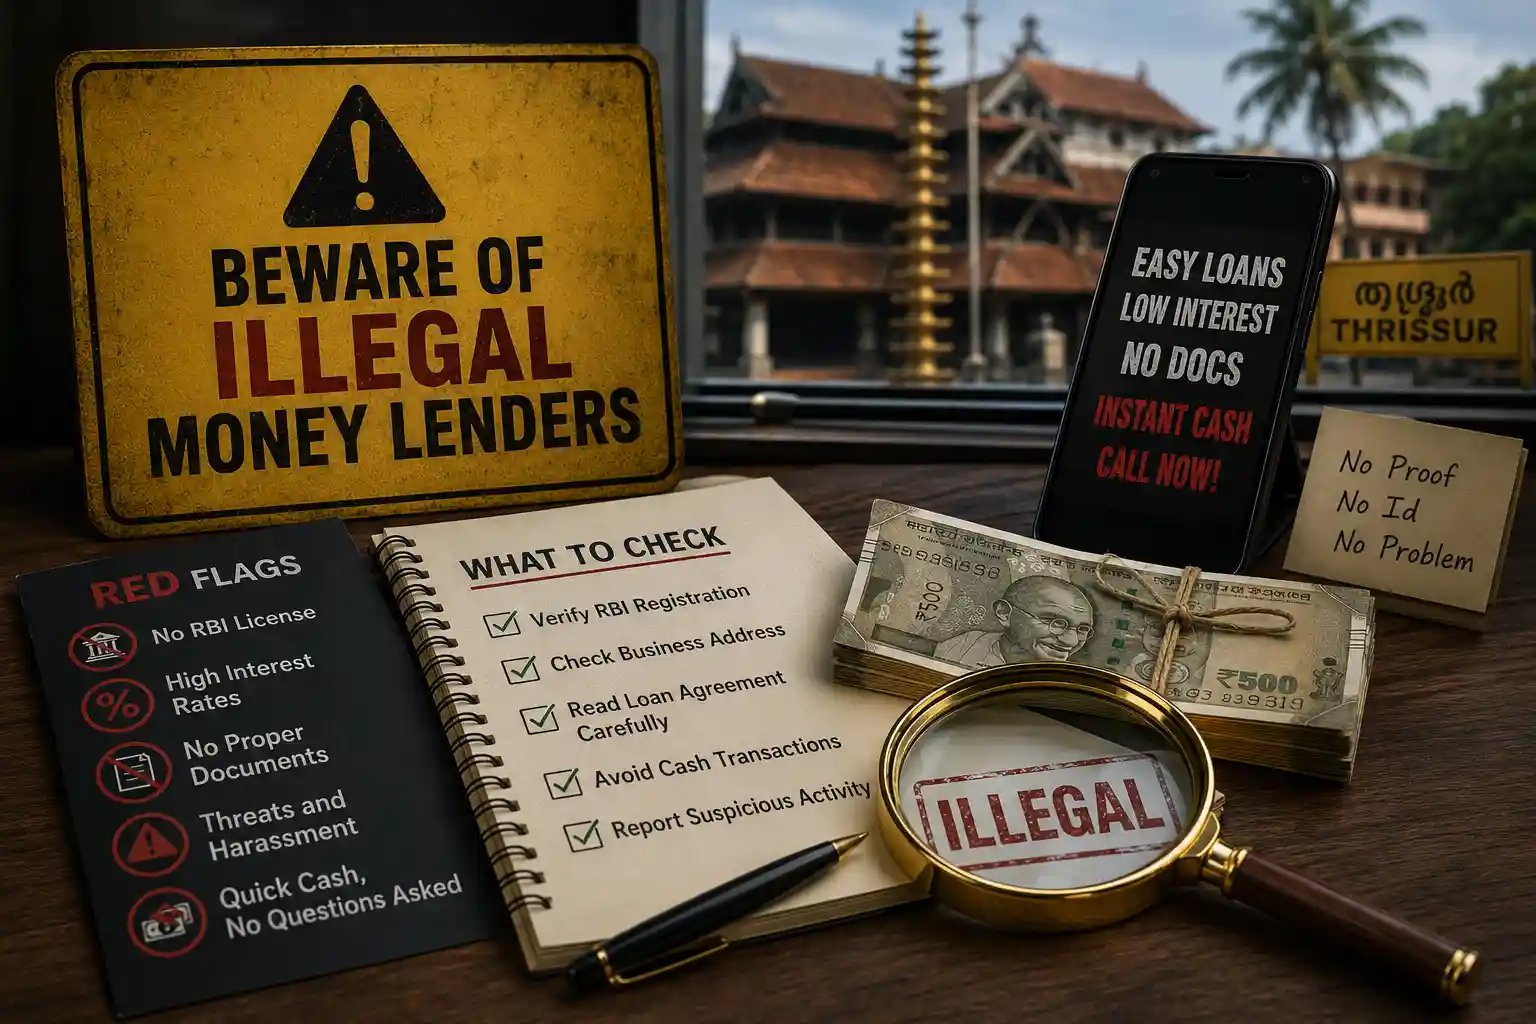
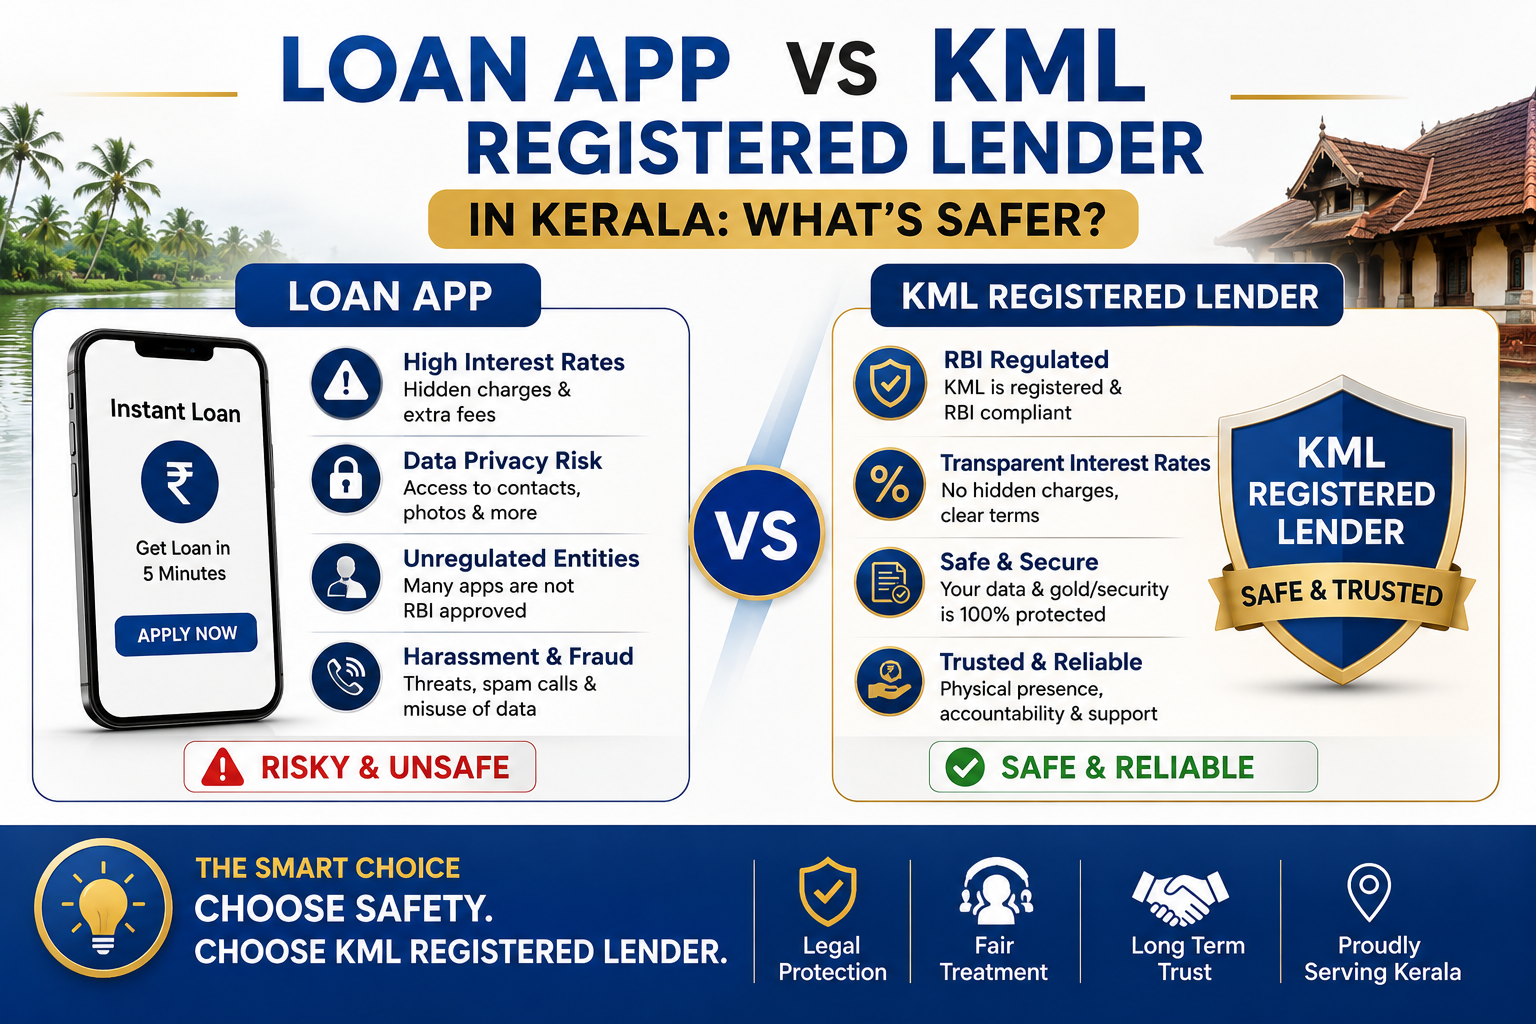
Unregistered lenders, by contrast, can set arbitrary terms, use aggressive recovery tactics, and offer no legal recourse if disputes arise.
NBFC vs Private Financier Kerala: What’s the Difference?
Understanding NBFC vs private financier Kerala distinctions helps you answer the safety question more precisely.
NBFCs (Non-Banking Financial Companies)
- Regulated by the Reserve Bank of India
- Larger loan amounts, structured products
- Formal documentation and credit checks
- Often slower approval than local financiers
KML-Registered Private Finance Companies
- Regulated under the Kerala Money-Lenders Act, 1958
- Faster approval, especially for gold and micro loans
- Local presence and personalised service
- Interest rates capped by state regulation
Unregistered/Informal Lenders
- No regulatory oversight
- Interest rates can be arbitrary and high
- No standardised agreements
- Limited legal protection for borrowers
Knowing which category a lender falls into is the single most important step in assessing risk.
How to Verify a Finance Company Before Borrowing
Here’s how to verify a finance company operating in Kerala before you sign anything:
- Ask for KML registration proof. A licensed lender Guruvayoor or anywhere in Kerala should readily share their registration certificate under the Kerala Money-Lenders Act.
- Check the interest rate structure. Registered lenders disclose rates upfront, with no hidden or compounding charges beyond legal limits.
- Review the loan agreement. A legitimate loan company Kerala always provides a written, signed agreement — never a verbal-only arrangement.
- Verify the physical branch. Confirm a real, verifiable office address, not just a phone number or WhatsApp contact.
- Look for transparent recovery practices. Lawful lenders follow structured notice periods; they don’t threaten or harass borrowers.
Risks of Borrowing from Private Financiers
The risks of borrowing from private financiers who operate outside KML regulation include:
- Unregulated interest rates — often far above legal limits, compounding quickly
- Coercive recovery methods — threats, public shaming, or unlawful asset seizure
- No dispute resolution — informal lenders offer no grievance redressal mechanism
- Hidden charges — processing fees, penalties, or foreclosure charges not disclosed upfront
- No receipt trail — cash-only dealings with no documented repayment history
Chit Fund Safety Kerala: A Related Concern
Chit fund safety Kerala follows similar principles — always confirm registration under the Chit Funds Act and check for a documented subscriber agreement before joining, since informal chit schemes carry many of the same risks as unregistered lending.
Private Financier Interest Rates: What’s Fair?
Private financier interest rates under KML regulation are capped and disclosed transparently, unlike informal lending where rates can escalate unpredictably. When comparing offers, always ask:
- What is the annual interest rate, and is it simple or compound?
- Are there processing fees, and how much?
- What happens with early repayment or foreclosure?
- Is there a written schedule of EMIs or repayment cycles?
A trusted NBFC Thrissur or registered financier will answer all of these clearly, in writing, before you commit.
Common Myths That Cloud the Safety Question
Myth 1: “All private financiers are unsafe.” Not true. Whether is it safe to borrow from a private finance company in Kerala depends on registration status, not the fact that a lender is “private.” Many KML-registered NBFCs operate more transparently than some larger institutions.
Myth 2: “Banks are always cheaper.” Not always. While banks often have lower headline rates, they also reject a large share of self-employed and informal-income applicants outright. A legitimate loan company Kerala operating under KML rules may charge slightly higher rates but offers access where banks won’t.
Myth 3: “If they have a website, they must be registered.” A professional website says nothing about legal compliance. Always verify registration documents directly — never assume legitimacy from branding alone.
Myth 4: “Cash-only lenders are just being flexible.” Cash-only dealings with no receipts are one of the biggest red flags among the risks of borrowing from private financiers. A licensed lender Guruvayoor or elsewhere in Kerala will always provide documented, traceable repayment records — digital or printed.
A Quick Borrower Checklist
Before signing any agreement, run through this checklist:
- ✅ Registration certificate shown and verifiable
- ✅ Interest rate disclosed in writing, with calculation method explained
- ✅ Physical branch address confirmed
- ✅ Loan agreement provided in full, not just a summary
- ✅ Repayment receipts issued for every payment
- ✅ No pressure to sign immediately without reading terms
If a lender fails even one or two of these checks, it’s worth pausing and comparing with a trusted NBFC Thrissur or KML-registered alternative instead.
Choosing a Safe Lending Partner in Guruvayoor
Abrus Krishna Finance operates as a KML registered finance company based in Guruvayoor, combining local accessibility with full regulatory compliance. Every loan — from gold-backed to micro business lending — follows a documented, transparent process under the Kerala Money-Lenders Act.
If you’re evaluating lending options, explore:
- About Us — learn about KML registration and company background
- Gold Loan — transparent, collateral-backed lending with disclosed rates
- Business Loan in Guruvayoor — structured lending for small businesses and self-employed borrowers
Frequently Asked Questions
1. Is it safe to borrow from a private finance company in Kerala? Yes, provided the lender is registered under the Kerala Money-Lenders Act. Safety depends almost entirely on regulatory compliance, not just reputation.
2. How do I know if a lender is KML-registered? Ask directly for their registration certificate, or check whether they disclose interest rates, provide written agreements, and follow transparent recovery practices.
3. Are private financiers more expensive than banks? Not necessarily. Registered financiers operate within capped interest rates, though rates can vary by loan type — always compare before committing.
4. What should I do if a lender uses unfair recovery practices? You can report unlawful recovery methods to local authorities, since the Kerala Money-Lenders Act prohibits coercive or harassing collection tactics.
5. Are gold loans from private companies safer than personal loans? Generally yes, since they’re collateral-backed and valuation-based, reducing dependence on income documentation — but the lender’s registration status still matters most.
Final Thoughts
So, is it safe to borrow from a private finance company in Kerala? It comes down to one question: is the lender registered and transparent? Checking KML registration, reviewing agreements, and confirming a physical branch protects you from the real risks of informal lending.
Considering a loan? Verify, compare, and borrow safely. Contact Abrus Krishna Finance →
📍 Abrus Krishna Finance, Sreekrishna Enclave, Thaikad (PO), Guruvayoor, 680508 📞 +91 8086155888 | ✉️ info@abruskrishna.com